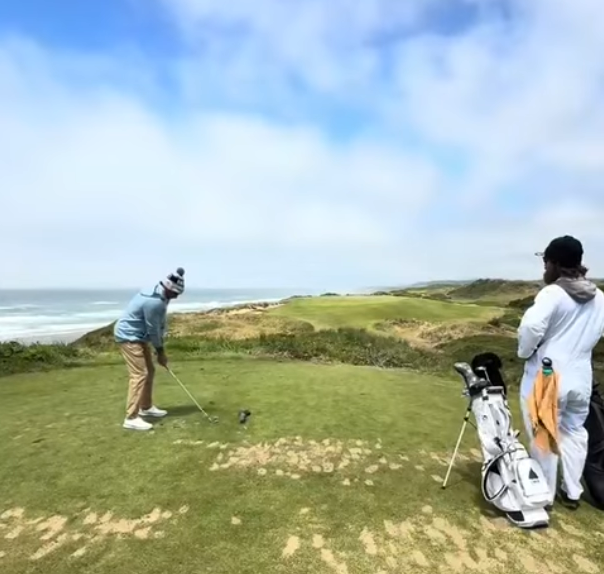
As most of you know, I love to play golf. And I've been fortunate enough to play some pretty spectacular golf courses over the years, including Bandon Dunes in Oregon.
If you're not familiar with Bandon Dunes, it's a pretty special place for us golf junkies. A round of golf can run upwards of $400. And if you want a caddie? Figure another $150 or so.
Is it worth it? Well, that depends. And if you've ever talked financial planning with me, you know those are two of my favorite words.
“It depends.”
On your circumstances. Your priorities. And what you VALUE.
I've played golf most of my life. I know how to read greens, calculate yardages, and figure out which club to hit. I certainly don't NEED a caddie.
But having a caddie at Bandon Dunes? Absolutely worth it to me.
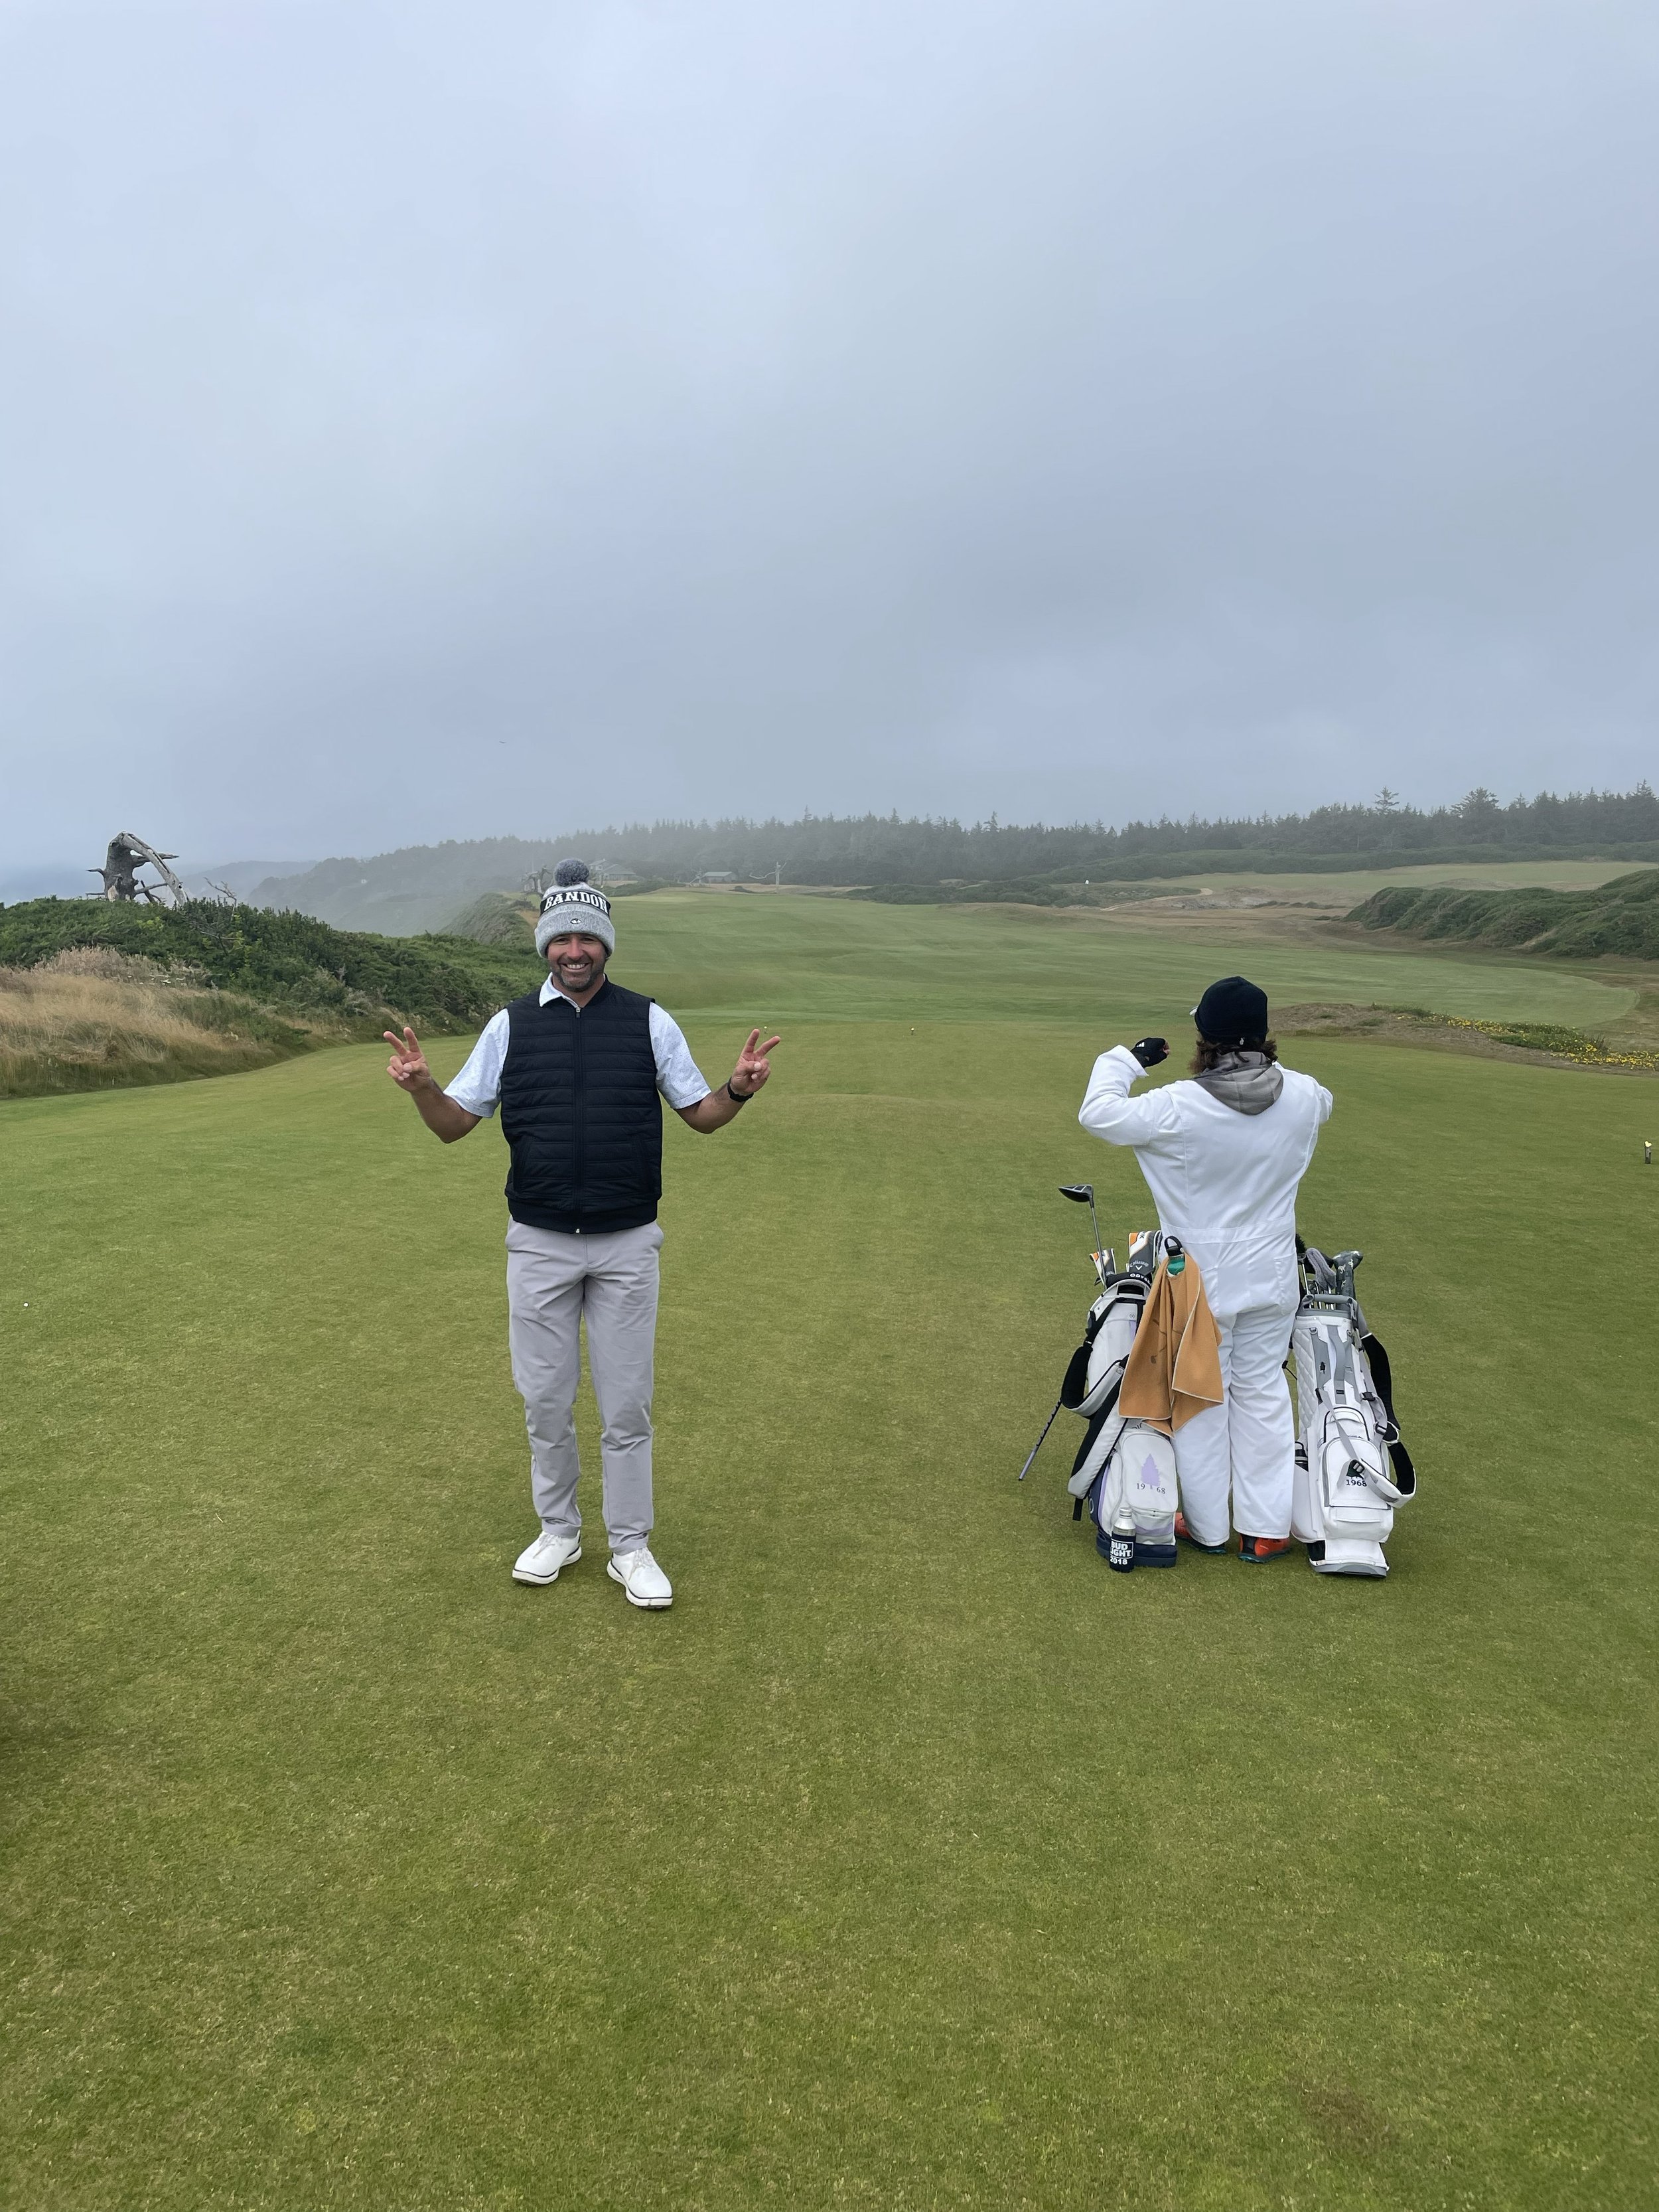
We had the same caddie all week. Not only did he know the golf courses, but he was getting to know MY golf game. He picked up on the types of shots I liked to play. He knew which clubs I preferred to hit in certain situations. He knew where I needed to hit the ball and, perhaps more importantly, where I absolutely did NOT want to hit it.
His advice became more valuable as he got to know me. And maybe, just maybe, he talked me out of hitting a shot or two I had no business trying to hit.
There's real VALUE in that.
And there's something else. Having a caddie allowed me to enjoy the experience a little differently. I could spend less time thinking about some of the decisions and more time enjoying the round of golf.
Now, another golfer might think paying another $150 for a caddie is ridiculous. Same golf course. Same price for a caddie. Two very different perceptions of VALUE. And neither of us is wrong.
And that's how I think about the price of financial advice.
Regardless of how your financial advisor gets paid, I think the question you should be asking yourself is this: Am I receiving—and seeing—the VALUE?
Because price and value are two very different things. And while the price might be the same for two people, the value they see in that relationship might be entirely different. Which brings me to one of the more interesting conversations I have with potential clients.
How I get paid.
Fee-Only vs. Flat-Fee
First, let's clear up a little confusion.
A fee-only financial advisor is compensated solely by their clients, rather than receiving commissions for selling financial products. That compensation might come in the form of an hourly fee, a flat fee, or a percentage of the investments they manage (commonly referred to as an assets under management, or AUM, fee).
A flat-fee financial advisor charges a predetermined dollar amount for an agreed-upon set of services.
So a financial advisor can be fee-only without being flat-fee. But a flat-fee advisor who receives compensation solely from clients is also fee-only.
Clear as mud? Good. Let's keep going.
What Are You Actually Paying For?
Let's say you have $1 million in investments and you're paying your financial advisor an annual fee of 1%. That's $10,000 per year.
Now let's say your investments grow to $2 million. Assuming that same 1% fee, you're now paying $20,000 per year.
Here's my question: Has your financial life become twice as complicated?
Maybe. Maybe not.
Now, let me be clear. I don't have a problem with someone paying their financial advisor $20,000 a year. Or $30,000. Or whatever the fee might be.
What matters to me is whether you're receiving—and seeing—the VALUE in that relationship. And that's going to look different for everyone.
One of the reasons I built my business around a flat-fee model is that I believe the price of financial advice should reflect the work we're doing together.
Financial Planning Is More Than Your Investments
I've written before about how life isn't a straight line. And neither are our financial lives. We change jobs. We get married. We have kids. We buy houses. We inherit money. We retire. Sometimes things go according to plan. Sometimes they don't. And all along the way, we're making financial decisions.
Should I pay down my mortgage or invest that money?
Am I saving enough to retire when I want to retire?
Should I exercise my stock options?
How do I turn all of these retirement accounts into a paycheck when I stop working?
And what about taxes?!
These are the conversations I have with clients. Sure, we talk about investments. Investments are an important part of the equation. But they're not the ENTIRE equation.
And quite often, the value of having a financial advisor has very little to do with what the stock market did last year.
Think back to my caddie at Bandon Dunes. The longer we worked together, the better he understood my golf game. And the better he understood my golf game, the more valuable his advice became.
I think the same can be said about a good financial planning relationship.
Over time, your financial advisor gets to know you. Your family. Your goals. Your concerns. How you think about money and how you make financial decisions.
And sometimes the greatest value isn't helping you make another birdie. It's helping you avoid a double bogey.
Is Flat-Fee Financial Planning Right for Everyone?
Nope.
Some folks simply want someone to manage their investments. Others enjoy managing their own financial lives and might benefit from an occasional conversation with a financial planner.
And some folks prefer paying an advisor based on the amount of money that advisor manages. Nothing wrong with that.
But if your financial life has become more complicated, if you're juggling a number of financial decisions, or if you'd simply like to have someone in your corner helping you make sense of it all, comprehensive financial planning might be a good fit.
And a flat-fee relationship might make sense if you:
Want to know what you're paying for financial advice.
Value ongoing financial planning, not just investment management.
Want help making financial decisions across your entire financial life.
Prefer an ongoing relationship with someone who knows you, your family, and your goals.
Notice I didn't say anything about the size of your investment portfolio?
A Final Thought
When you're evaluating a financial advisor, I'd encourage you to look beyond the fee itself.
What services are you receiving? How often will you communicate? Is the advisor helping you with your entire financial life, or just a portion of it? And perhaps most importantly, are you seeing the VALUE in the relationship?
Because regardless of how your financial advisor gets paid, that's what matters.
Remember, I don't NEED a caddie to play a round of golf. But just because I'm capable of doing something on my own doesn't mean there isn't value in having someone alongside me.
The same can be said about managing your financial life.
At OnPlane, I've chosen to charge a flat fee because I believe it's a good way to align the price of financial advice with the work we're doing together.
It's not just about managing your money. It's about helping you manage your financial life.
Looking for someone who knows your financial game, like a good caddie?